IAMGold (TSX: IMG) shares have been quite explosive, gaining more than 853% in just five years, thanks in part to the impressive run-up in gold prices, which has since taken a bit of a breather. While the big banks are still quite upbeat about the prospects for gold from here (still a respectable amount of upside according to some big-name firms, thanks in part to the ongoing debasement trade), it’s the miners (big and small) that stand to get an even more noticeable leg higher.
Indeed, the miners are a more explosive, volatile trade than the likes of the physical asset itself. For a mid-cap miner like IAMGold, which boasts a $16.1 billion market cap, the volatility has been taken up a few notches. Shares have a 2.34 beta at the time of this writing, which is a much rougher ride than investors would get with the likes of a larger-cap rival.
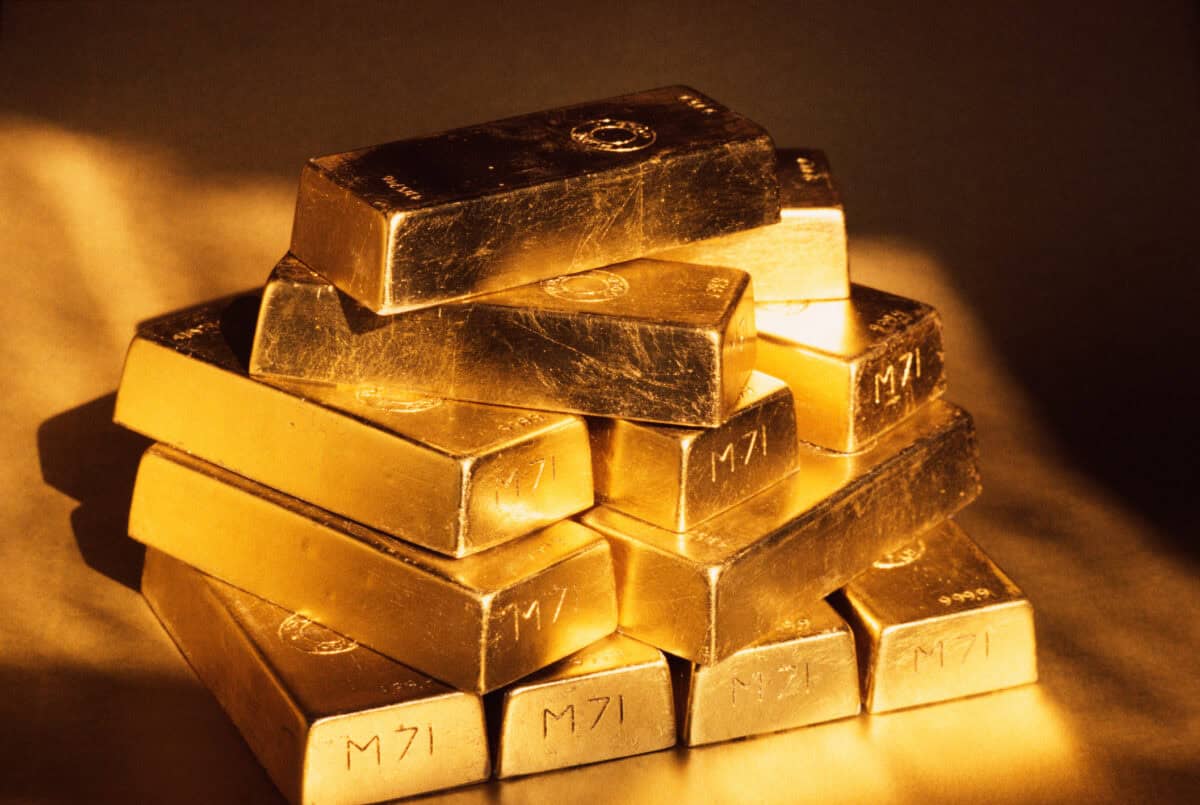
For now, the big question on the minds of investors is whether it makes more sense to own physical bullion (a coin in your drawer or a physical gold exchange-traded fund) or one of the miners for added torque and operational leverage. For those craving a higher risk/reward, perhaps a more junior member in the latter camp could make sense on a pullback. Personally, I think physical gold and the miners fit very nicely together, serving different purposes for a portfolio.
Source: Getty Images
IAMGold stands out as a great miner to stash away
As a less volatile asset than miners, physical gold is a terrific ballast for a portfolio, while miners are, at least in my view, an incredibly undervalued way to play amplified upside for those fine with the potential for amplified downside risks. Indeed, the miners are more sensitive to labour costs, inflationary pressures, and all the sort. In my humble opinion, much of the gold-mining space seems quite cheap unless, of course, you expect a crash in gold prices, in which case the low valuation multiples might be nothing more than a siren song for deep-value seekers and gold bugs.
I guess it all comes down to whether you believe in the asset and the value it can provide to your portfolio. Yes, the U.S. debt is getting up there, but at the same time, rates are another question mark. The good news is both factors are probably already priced into the asset. For the miners, though, I think there’s an extra layer of upside that, dare I say, might not be fully priced in with some of the smaller-cap miners out there.
When it comes to IAMGold, the stock looks like a parabolic gainer that’s exhibiting technical weakness, and the chart certainly looks a bit uneasy to get behind with new money. That said, when you consider the fundamentals (and they’re strong) and the mere 8.9 times forward price-to-earnings (P/E) multiple, it’s my opinion that IAMGold might still be misunderstood and underestimated.
The bottom line
With a steadily improving balance sheet, plenty of projects that could further bolster production, and growing evidence of improving cost structure, I certainly wouldn’t bet against shares of IMG. For long-term investors bullish on gold, I think there’s real value to be had, even though the chart may suggest otherwise. While I am bullish in the long term, I acknowledge that things could go either way in the near term. As such, I’d be a buyer, but a cautious, incremental buyer on the way down. Maybe buying in fifths could make a lot of sense in the coming months, especially as gold’s recent run reverses course.